














Lending
A loan book that keeps its own ledger.
For NBFCs, credit societies and other lenders. Enquiries to collections, with KFS and RBI asset classes.
- Works today on the demo company
- Live demo sign-in from us, on request
- Your server or MyRecords Cloud

- Built for you
- Customised
- to your requirements, by our team
- Users
- Unlimited
- no per-user fees, on any module
- Runs on
- Your server or MyRecords Cloud
- a dedicated system, in any country
What it fixes
What changes with Lending.
In short
Lending in MyRecords is a loan book for NBFCs, credit societies and other lenders: loan products, enquiries and applications with FOIR, LTV and a bureau tab, Key Facts Statement and sanction letter PDFs, disbursement, repayment schedules, collections and restructuring. Loans are grouped by RBI asset class (Standard, SMA-0, SMA-1, SMA-2, NPA) from days past due, and interest, dues and repayments post to the same ledger as the rest of the business. It records and supports your process; compliance with RBI rules stays with you as the lender.
-
Before: Applications live in WhatsApp chats and a shared Excel sheet.
With Lending: Every application sits on a board by stage, with documents uploaded in place and a decision log.
-
Before: The KFS is typed by hand and the APR worked out on a calculator.
With Lending: The KFS prints from the application, with the APR worked out from the loan's cash flows as in RBI's 2024 circular.
-
Before: A loan that slipped to SMA-2 shows up only at month-end.
With Lending: The loans board groups every loan by RBI class from days past due, and the nightly run keeps it current.
-
Before: Collectors call whoever they remember.
With Lending: Collections lists dues by today, overdue, this week, promised and broken promises, worst first, with a risk score per loan.
-
Before: The loan book and the accounts never agree.
With Lending: Interest accrual, dues and repayments post to the ledger, with loan interest receivable kept apart from trade debtors.
What it does
What Lending does for you.
Everything here works today on the demo company.
- 01
Lending home
The loan book as on any date: portfolio outstanding, overdue, portfolio at risk (30+ days), NPA and collection efficiency, charts by days past due, and lists to call and collect. EMI calculator, Portfolio summary (PDF) and Explain my book.
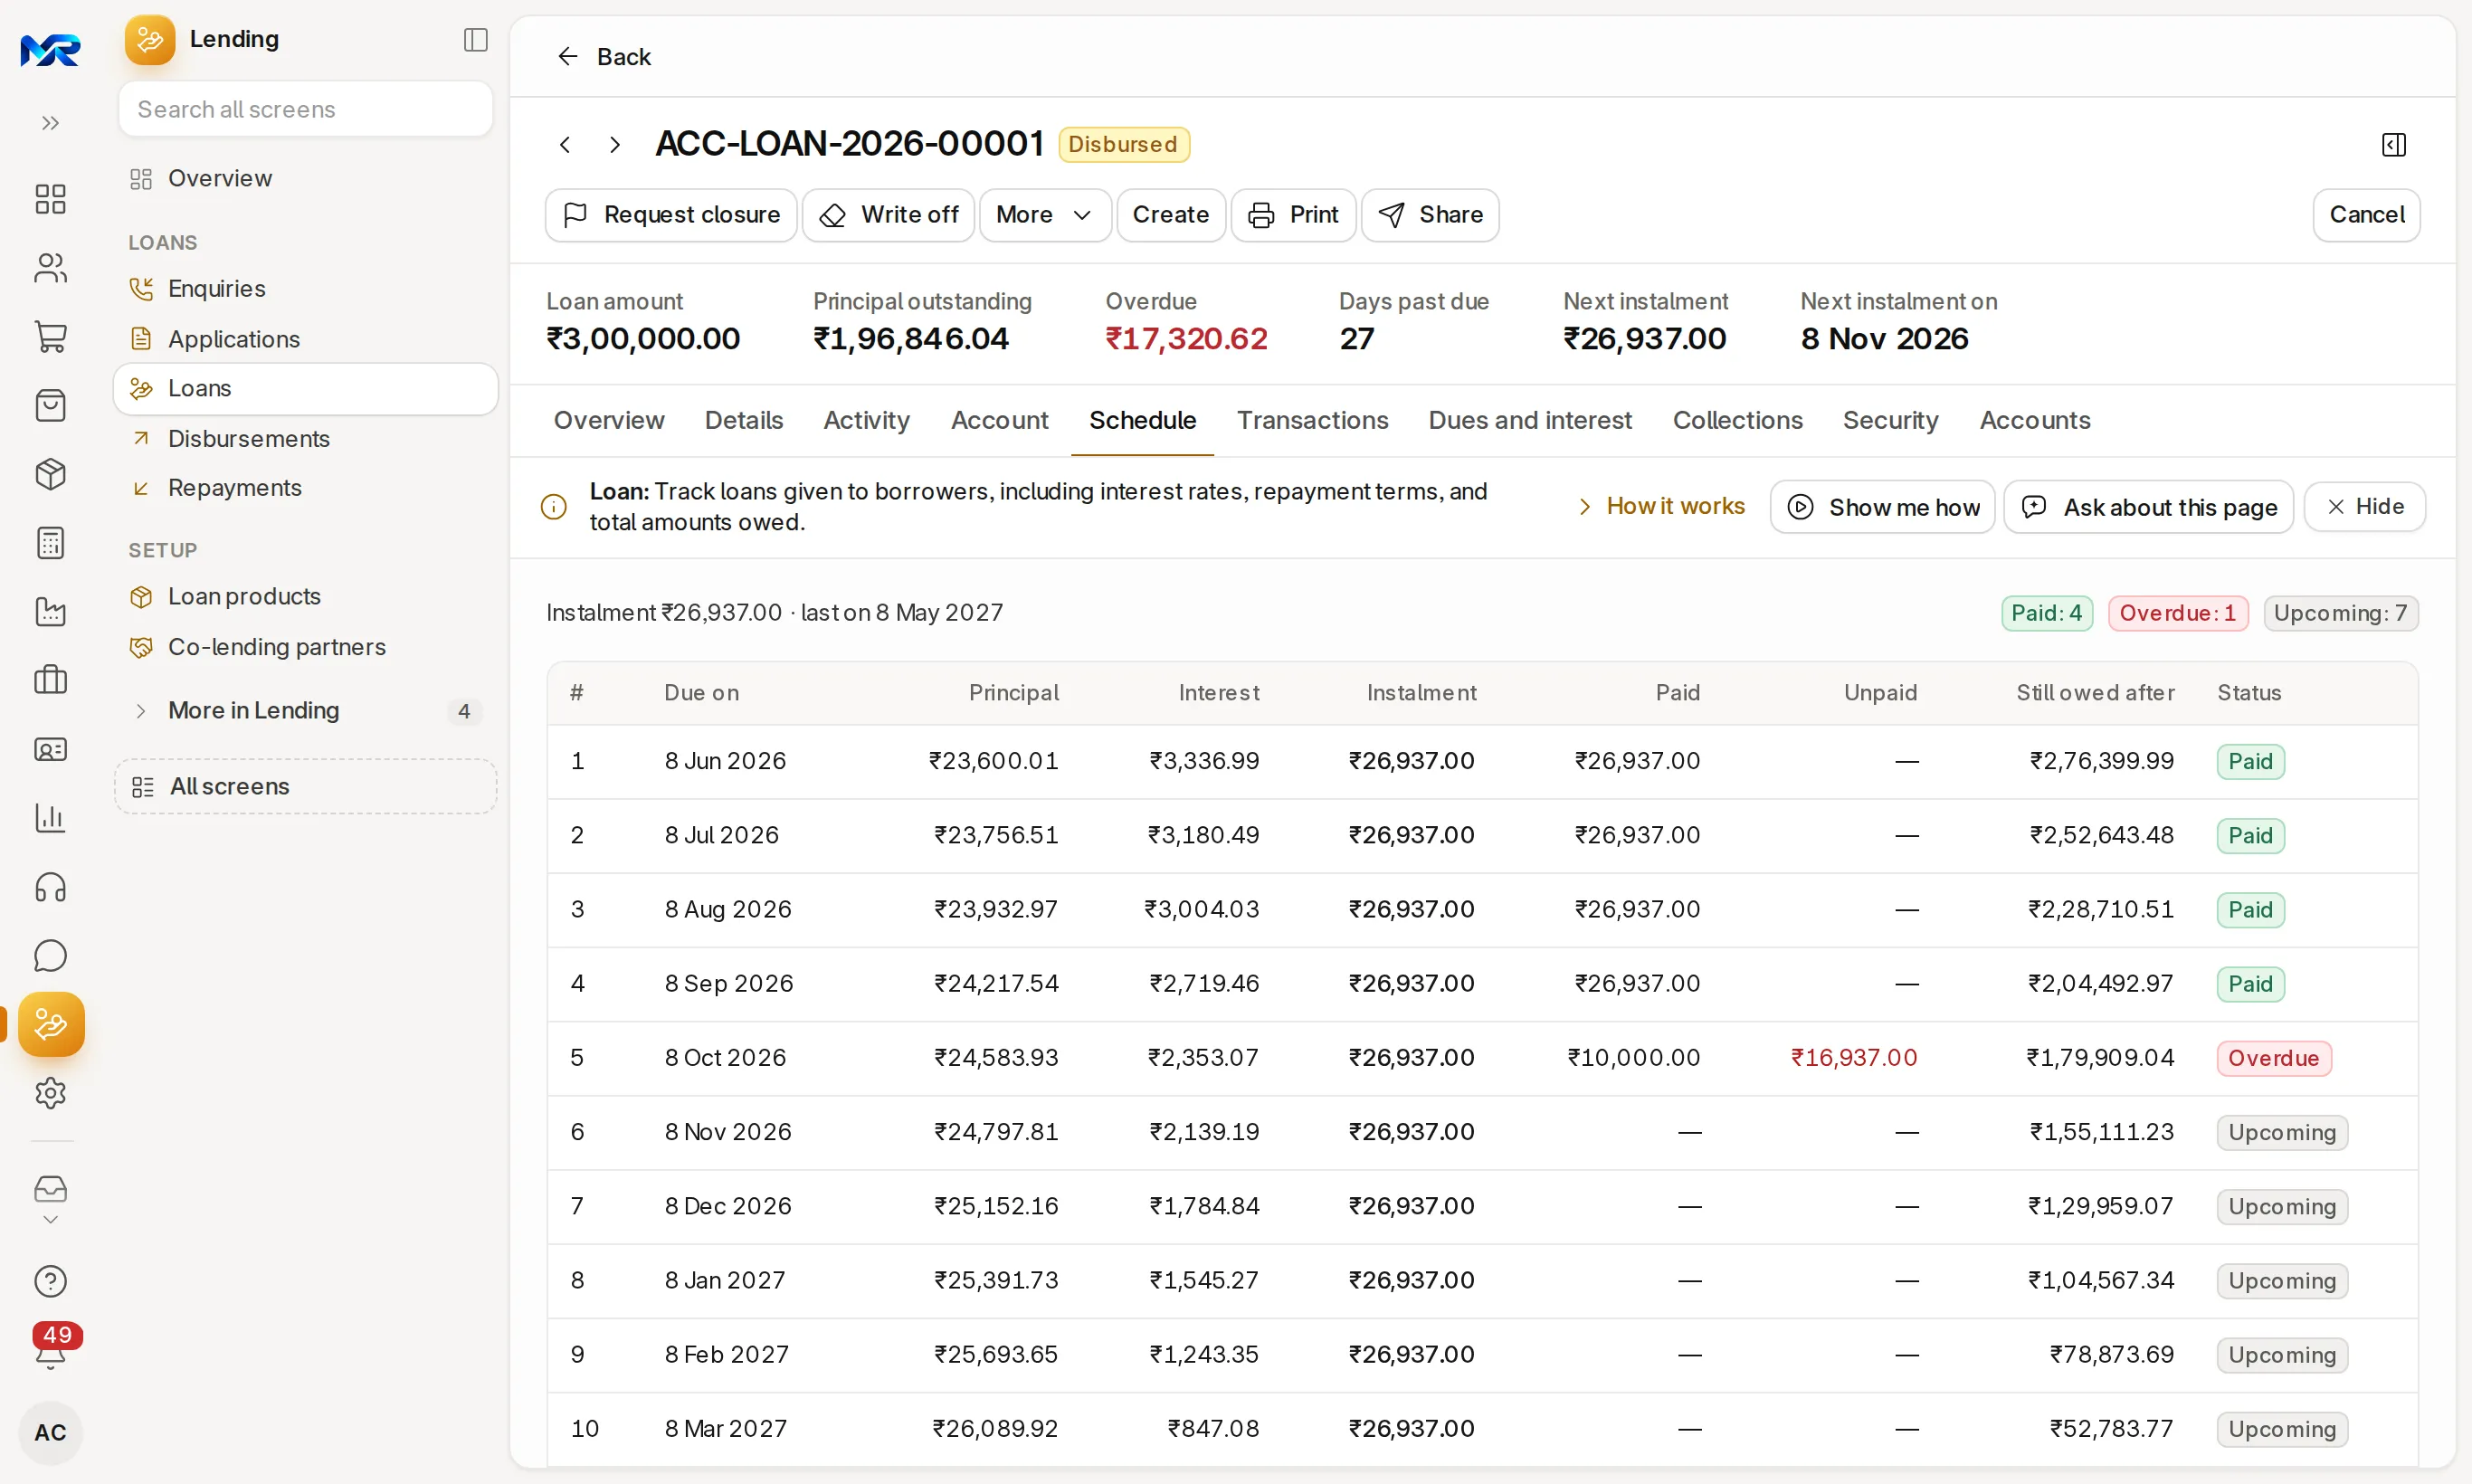
A loan’s repayment schedule on the sample company. - 02
Loan products
Rate, tenure, charges and ledger accounts per product, with a check of the accounts still to set and the documents an applicant must give. Lend to customers or to your own employees.
- 03
Enquiries and applications
Enquiries from walk-ins, calls or a public form, with an instalment check and a one-time code to verify. Applications on a board by stage: FOIR, LTV and EMI, a bureau tab, a duplicate-borrower check and a decision log.
- 04
KFS and sanction letter
The Key Facts Statement with the loan's cost figures and APR, and a sanction letter, as PDFs. E-mail the KFS and record the borrower's acknowledgement.
- 05
KFS in 12 languages
Hindi, Bengali, Marathi, Telugu, Tamil, Gujarati, Kannada, Malayalam, Odia, Punjabi, Assamese or Urdu, under each English line. Needs AI Assistant on; a Loan Manager can correct the wording.
- 06
Disbursement and schedules
Pay out in full or in tranches, mark a payout cleared with its UTR, and download a NEFT payout list for many. The loan gets its schedule with principal, interest and balance per instalment.
- 07
Loans board by RBI class
Standard, SMA-0, SMA-1, SMA-2 and NPA, from days past due, with each company's own day ranges. From the loan, restructure, refund, apply a charge, write off or freeze, and track pledged security.
- 08
Collections
Due today, overdue, this week, promised and broken promises. Assign a collector, log a call or visit, record a promise to pay. WhatsApp reminders go only between 08:00 and 19:00.
- 09
Repayments
Record a repayment, part-prepayment or foreclosure, or many at once from your bank's CSV file. Receipt PDF, send receipt, mark as bounced with a charge. Employee loans can be recovered from salary.
- 10
Co-lending partners
Each partner's share of the book, the first-loss (FLDG) terms and RBI checks (you keep at least 10%, FLDG at most 5%), with a payout statement by date as CSV.
India compliance
For businesses in India, built in.
India is our first fully supported market. Each line says whether it works today, once you connect your account, or in part.
Outside India
These lines follow RBI rules for lenders in India. Outside India, ask us what your regulator needs before you plan.
What works in your country- Works today
RBI asset classes
Standard, SMA-0/1/2 and NPA by days past due, with the day ranges set per company. A borrower's other running loans turn NPA with the first one.
- Works today
KFS figures as RBI asks
The KFS shows amount, term, instalments, interest, fees, net disbursed and total payable, with the APR worked out as in the illustration to RBI's KFS circular of 15 Apr 2024.
- Works today
Calling hours
WhatsApp reminders to borrowers are sent only between 08:00 and 19:00, in line with RBI's directions on recovery.
- Works today
Borrower's language
The KFS prints in 12 Indian languages under the English, with "English version prevails". Names and figures never go to the AI.
- Works today
Consent and CKYC
Bureau consent is recorded with its time, and the CKYC number is stored encrypted on the application.
Try it
See it on the demo company.
We show you the live system on a call: five sample loans with schedules that add up and end at zero, an application with its KFS, and the loans board by class. Ask for a demo sign-in to explore it yourself, or join the pilot programme with your own loan book.
Reports and roles
What you see, and who sees it.
Reports come ready on day one. Each person sees only the screens and records their role allows.
Reports you get
- Lending home (portfolio outstanding, overdue, portfolio at risk, NPA, collection efficiency)
- Loans by RBI class (Standard, SMA, NPA)
- Collections (due today, overdue, this week, promised, broken promises)
- Unpaid loan balances, Loan account statement and Loan repayment summary
- Expected loan cashflow, Past loan cashflow and Loan payout summary
- Asset liability audit
- Collateral reports (loan collateral status, ledger and risk)
- Portfolio summary (PDF)
- Co-lending payout statement
- Statements and runs (statement runs to borrowers; what each nightly run booked)
Who sees what
- Loan Manager
- See the whole book; approve, write off, run the nightly jobs on demand and correct KFS translations.
- Loan Officer, Appraiser, Processor, Underwriter
- Work enquiries, applications, loans, payouts and repayments, as each role allows.
- Loan Reporter
- See the book, reports and collections; log no calls and send no reminders.
- Collector
- Any staff member you assign loans to. They get the day's collections due each morning.
- Employee
- See only their own employee loan and application, nothing else.
Before you decide
What works today, and what does not.
Said plainly, so you can plan around it. What comes next is on the roadmap.
Works today15
On the demo company, now.
- Lending home
- Loan products
- Enquiries and applications
- KFS and sanction letter
- KFS in 12 languages
- Disbursement and schedules
- Loans board by RBI class
- Collections
- Repayments
- Co-lending partners
- RBI asset classes
- KFS figures as RBI asks
- Calling hours
- Borrower's language
- Consent and CKYC
Not in Lending yet
Left out on purpose, or planned.
- Credit bureau pull by API; attach the bureau report to the application for now.
- KFS acknowledgement on WhatsApp (e-mail works today).
- The KFS prints the cost figures and APR; the rest of RBI's format (recovery, grievance and cooling-off details) is not printed yet.
- Returns to RBI and data files for credit bureaus; the reports are for your own team and auditors.
- On a phone
- Works in any phone browser and installs to the home screen, so a collector can log a visit from the field. Lending needs a connection; only point of sale, the shop floor, attendance check-in, maintenance visits, asset physical checks and bill photos for Read a bill keep working offline.
- Bringing data in
- Borrowers, loan products and loan records through Import data (CSV, Excel or a Google Sheet): check the columns, then undo the import if needed. Repayments from your bank's CSV file. Moving running loans with their past disbursements and repayments is a separate data-migration job, quoted first.
- Getting data out
- KFS, sanction letters, receipts and statements as PDF; statements in bulk as a ZIP; the NEFT payout list, collections and co-lending payouts as CSV. Every list and report exports to Excel, CSV or PDF.
- Integrations
- E-mail works today. WhatsApp reminders and receipts work once WhatsApp Business is connected; until then a WhatsApp link opens on your phone. One-time codes by SMS need an SMS account (e-mail works today). Pulling a credit bureau report by API is not built yet; attach the report to the application.
- Where it runs
- Runs as your own dedicated system: on your server under an AMC, or on MyRecords Cloud for a monthly fee. The loan book and borrower data stay in your database, and you can export everything. Data ownership and exit
Questions
Questions people ask
Something else on your mind?
Ask us anything about modules, a quote or moving across. A person from our team replies.
Ask a question01Who is Lending for?
Lenders such as NBFCs, credit societies and businesses that lend to their customers or staff. It is not a loan for your business; it runs your own loan book.
02Does it make us RBI compliant?
No software can. Lending records your process, prints the KFS figures with the APR, and groups loans by asset class from days past due. Your policies, classification rules, returns and audits remain your responsibility.
03How is the APR on the KFS worked out?
From the loan's cash flows (amount, fees, net disbursed and instalments), as in the illustration attached to RBI's KFS circular. The KFS shows the figures it used.
04Can we set our own SMA and NPA day ranges?
Yes. Each company has its own days-past-due ranges for SMA-0, SMA-1, SMA-2 and NPA, and the loans board uses them.
05Do loan entries post to accounts?
Yes. Disbursement, interest accrual, dues and repayments post to the ledger. Loan interest receivable is kept apart from trade debtors.
06What does the AI do in Lending?
With AI Assistant on: Explain my book writes the portfolio in plain words, using only figures on the page; the KFS is translated into 12 languages; a PAN, Aadhaar or salary-slip photo fills an enquiry (Aadhaar photos are deleted after reading); and Explain this payout describes a co-lending statement. Everything else works with AI off.
07Can we lend to employees?
Yes. Tick Repay From Salary on the loan and the instalment comes off each salary slip (needs Payroll). An employee sees only their own loan and application.
08Is there a per-user charge for collectors?
No. Users are unlimited on every module. You pay for the modules you switch on, never per person.
Last updated Applies to MyRecords 3 Nov 2026 release
Next step
See it on your own numbers.
A live demo on our sample company, with the modules you would switch on. Or ask us for a quote first.
Live demo
Book a walk-through
- On our sample company, for your kind of work
- A quote for the modules you need
- Your questions, answered by our team